
The end of a sequential approach to hotel investment
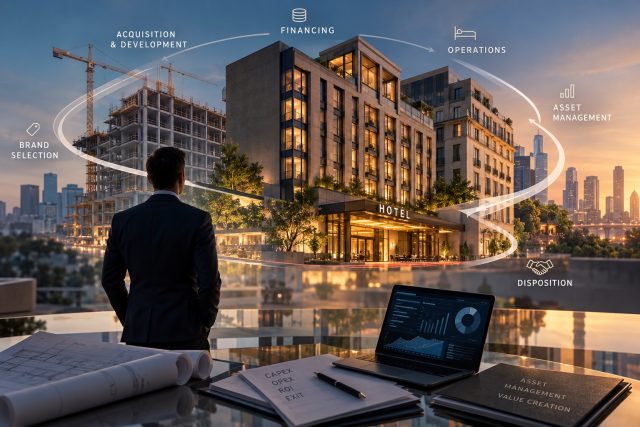
For many years, the hotel investment lifecycle was presented as a relatively straightforward progression: identifying an opportunity, acquisition or development, financing, operations, performance optimisation, followed by refinancing or disposal.
This framework remains useful for explaining the investment process. However, it increasingly fails to reflect the reality of the decisions facing hotel owners, developers and investors.
This is the argument developed by Preston Puleo, Executive Director and National Advisory Co-Lead, Hospitality & Leisure Valuation & Advisory at Cushman & Wakefield, in his report The Hotel Investment Lifecycle Is No Longer Linear (download the report here).
The author observes that the different stages of hotel asset ownership are becoming increasingly interdependent. A decision made at acquisition can influence operating margins, financing requirements or disposal conditions several years later.
Conversely, refinancing or disposal prospects may prompt an owner to reconsider an operating strategy, refurbishment programme or management agreement well before the end of the originally anticipated holding period.
Hotel investment can therefore no longer be reduced to a sequence of transactions. It has become a continuous process of financial, real estate and operational trade-offs.
Capital is becoming more expensive, but above all more selective
The first transformation identified by Cushman & Wakefield concerns access to financing.
In an environment characterised by higher financing costs, capital providers are placing increasing importance on the distinguishing characteristics of individual projects.
An attractive acquisition price, a location that is difficult to replicate, repositioning opportunities, potential operational improvements or access to public-sector incentives can all represent decisive advantages.
The question is no longer simply whether a property can be acquired, developed or financed. It is whether the investment can retain sufficient flexibility to absorb difficulties that may arise during the holding period.
This development is changing how hotel real estate risk is assessed.
A project offering attractive projected returns may prove vulnerable if its financial structure, contractual commitments or future capital expenditure requirements restrict the owner’s room for manoeuvre.
Conversely, an asset with clearly identifiable operational potential may offer greater opportunities for value creation, even in a constrained financing environment.
Brand selection becomes a long-term investment decision
One of the report’s most significant arguments concerns the consequences of decisions taken before a hotel even opens.
Brand selection, often considered primarily from a commercial or marketing perspective, actually carries numerous financial implications.
It can influence construction costs, fit-out requirements, future capital expenditure, operating cost structures, pricing positioning and operating margins.
It can also determine the profile of potential buyers interested in acquiring the property when it is eventually sold.
The same reasoning applies to hotel management agreements.
Performance clauses, termination provisions, management fees, owner approval rights and CAPEX obligations can have a lasting impact on an asset’s strategic flexibility.
An agreement suited to the original development assumptions does not necessarily remain optimal when market conditions, financing structures or investor objectives change.
For Cushman & Wakefield, decisions concerning brands and operating partners should therefore be examined as components of the investment strategy rather than simply operational choices.
Capital structure: an instrument of governance as well as financing
The report emphasises a second factor that is frequently underestimated: capital structure determines more than the cost of financing.
It also shapes risk allocation, decision-making rights, recapitalisation options and investors’ ability to respond to changing market conditions.
Financing that appears attractive in terms of cost may become restrictive if it limits refinancing opportunities, imposes restrictive conditions or reduces the freedom to undertake additional investment.
The choice between different forms of debt, equity and intermediate financing therefore cannot be separated from the operating strategy and anticipated holding period.
This perspective requires investors to look beyond comparisons of interest rates and financing costs alone.
Debt maturity, covenants, early repayment options, financial partners’ rights and distribution restrictions must all be assessed against the property’s future requirements.
This relationship between financial strategy and real estate management can also be seen in the reorganisation of Gencom around two divisions, Capital and Real Estate, illustrating the importance of a coordinated approach to investment and asset valuation.
Capital is no longer merely a resource used to acquire or develop a hotel. It has become a determinant of governance and strategic flexibility.
Operations once again become a central driver of value creation
Cushman & Wakefield also identifies a shift in the sources of hotel investment performance.
When financing conditions are favourable and real estate values are rising broadly, part of the value created may result from market movements themselves.
In a more selective environment, the quality of operational execution becomes increasingly important.
Revenue optimisation, cost control, capital expenditure planning and management discipline can determine whether initially projected returns are actually achieved.
This development reinforces the role of hotel asset management.
The asset manager’s responsibilities now extend beyond performance monitoring and budget oversight. They include balancing capital investment against cash distributions, assessing refinancing opportunities, monitoring operator commitments and preparing different strategic options.
Managing RevPAR, operating profitability and CAPEX requirements therefore takes on its full significance within a real estate valuation framework.
An improvement in operating profit can support asset value, but its impact also depends on the sustainability of that performance, future expenditure requirements and market conditions at the time of disposal.
Exit strategy begins at acquisition
One of Preston Puleo’s central arguments is that preparation for a hotel disposal begins long before the property is brought to market.
The final sale price depends on more than real estate market conditions or the effectiveness of the marketing process.
It also reflects decisions made years earlier: brand selection, the nature of the management agreement, financial structure, building maintenance, refurbishment schedules and competitive positioning.
These decisions influence both the property’s value and the number of investors likely to consider acquiring it.
An asset burdened by rigid contractual commitments, substantial refurbishment requirements or debt that is difficult to restructure may be less attractive than a property offering greater flexibility.
The report therefore emphasises that an investment’s future liquidity is shaped throughout its holding period.
This approach challenges the practice of treating exit strategy as a consideration that begins only when an owner decides to sell.
Coordination between disciplines becomes critical
Beyond financial and operational considerations, Cushman & Wakefield highlights a growing challenge: complexity often arises at the intersection of different areas of expertise.
An architectural decision can change operating costs. An increase in the construction budget can affect financing. A repositioning decision may require contractual renegotiation and alter disposal prospects.
Investors generally have access to specialists in each discipline: valuers, financial advisers, developers, architects, operators, legal advisers and asset managers.
This search for complementary financial and operational expertise is also reflected in the combination of Cycas Hospitality and Vertiq Capital, which led to the creation of Vertiq Hospitality Partners, bringing together investment expertise and hotel operating know-how.
The challenge now lies in integrating their analyses to make coherent decisions at asset level.
The study therefore advocates a cross-disciplinary approach in which every major decision is assessed in terms of its consequences for other aspects of the investment.
This requires closer cooperation between real estate, financial and operational functions, together with regular reassessment of the assumptions established at acquisition.
LTH Analysis | From hotel operating performance to returns on invested capital
Cushman & Wakefield’s principal contribution is to demonstrate that hotel value creation cannot be separated from an asset’s contractual and financial structure. An improvement in EBITDA does not, in itself, guarantee a satisfactory investor return if it requires disproportionate CAPEX or if financing costs absorb an excessive share of cash flow. Similarly, a management agreement that delivers strong commercial performance may reduce an asset’s attractiveness on resale when its provisions restrict repositioning opportunities. This interdependence reinforces the need for asset management capable of balancing immediate profitability, property preservation, financial flexibility and exit value. Hotel investment performance must now be assessed across the entire holding period rather than through a succession of isolated indicators.
At a Glance by The Hospitality Tribune
Hotel investment: the lifecycle is no longer linear
Report: The Hotel Investment Lifecycle Is No Longer Linear, by Cushman & Wakefield.
Author: Preston Puleo, Executive Director, Hospitality & Leisure Valuation & Advisory.
Key drivers: Higher capital costs, longer holding periods and growing operational complexity.
Investment strategy: Brand selection, management agreements and capital structures increasingly influence future flexibility and exit options.
Value creation: Operational execution, disciplined asset management and capital planning play a greater role in investment outcomes.
Main conclusion: Successful hotel investors manage the interdependencies between acquisition, operations, financing and disposal, rather than treating them as separate stages.