
Seven hotels sold to two separate investor groups
On 22 October 2026, Pandox announced two agreements to sell seven hotel properties from its Leases segment, comprising assets leased to hotel operators.
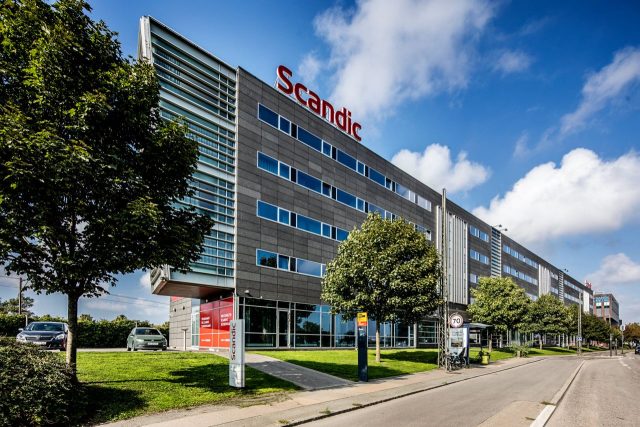
The first transaction involves five Danish hotels comprising 928 rooms. They are being acquired by a company jointly owned by Alma Property Partners and Midstar AB.
The underlying property value amounts to DKK 1.155 billion, equivalent to approximately SEK 1.7 billion, before deduction of deferred tax.
The second transaction involves two Swedish hotels totalling 320 rooms. The buyer is Västerkulla Hotell AB, with an underlying property value of SEK 369 million, also before deduction of deferred tax.
The seven properties are:
| Property | Location | Rooms |
|---|---|---|
| Scandic Sluseholmen | Copenhagen, Denmark | 215 |
| Scandic Hvidovre | Hvidovre, Denmark | 207 |
| Motel One Copenhagen | Copenhagen, Denmark | 200 |
| Scandic Kolding | Kolding, Denmark | 186 |
| Scandic Glostrup | Glostrup, Denmark | 120 |
| Scandic Hallandia | Halmstad, Sweden | 170 |
| Scandic Kalmar Väst | Kalmar, Sweden | 150 |
| Total | 1,248 |
Both transactions are expected to close during the fourth quarter of 2026.
The announcement states that their combined valuation exceeds the properties’ book values as at both 30 September 2026 and 30 September 2025.
An implied property yield of approximately 6.2%
According to Pandox, the seven properties generated a combined annual property net operating income of approximately SEK 130 million.
Relative to the announced property value of SEK 2.1 billion, this represents an implied property yield of approximately 6.2%.
This ratio, calculated from the disclosed figures, should be regarded as indicative. It is based on the properties’ annual income and their underlying property value before deduction of deferred tax, rather than the final net proceeds from the disposals.
The average valuation amounts to approximately SEK 1.68 million per room across the portfolio being sold.
However, the two transactions have different profiles:
| Metric | Denmark | Sweden |
|---|---|---|
| Number of hotels | 5 | 2 |
| Rooms | 928 | 320 |
| Property value | ≈ SEK 1,700 million | SEK 369 million |
| Average value per room | ≈ SEK 1.83 million | ≈ SEK 1.15 million |
| Buyers | Alma Property Partners / Midstar AB | Västerkulla Hotell AB |
The difference in value per room cannot, in isolation, be interpreted as a difference in asset quality. It may reflect factors including location, lease structure, income generation or future capital expenditure requirements.
Pandox refocuses its Danish portfolio on Copenhagen
The Danish transaction has an additional strategic dimension.
Following the disposal, Pandox will retain three hotel properties in Denmark, comprising 912 rooms, all located in central Copenhagen.
The group is therefore disposing of several properties in suburban locations or regional markets while maintaining a concentrated presence in the centre of the capital.
This development forms part of an active real estate asset management strategy.
For a hotel property investor, location, depth of demand and potential asset liquidity play a decisive role in decisions to retain or dispose of properties.
The Danish portfolio adjustment therefore reflects selective asset management rather than a withdrawal from the market.
Expected deleveraging amid high financing costs
Pandox‘s interim report for the first nine months of 2026 provides the financial context for these disposals.
As at 30 September, the group reported:
- Net financial debt of SEK 50.58 billion.
- A net loan-to-value ratio of 52.2%.
- An average interest rate of 4.08%.
- A rolling twelve-month interest coverage ratio of 2.4 times.
According to management’s calculations, adjusting for the announced disposals would reduce the LTV ratio from 52.2% to 51.2%.
This one-percentage-point reduction is not insignificant for a group whose property portfolio is substantially debt-financed.
However, it does not, in itself, represent a fundamental change in the group’s financial structure.
Pandox also indicates that the increase in financing costs is attributable in particular to higher borrowing volumes following the Dalata acquisition, the expiry of certain favourable interest-rate hedges and higher benchmark interest rates.
In the third quarter, net financial expense amounted to SEK 635 million, compared with SEK 469 million a year earlier.
Debt reduction therefore represents a direct means of controlling the cost of capital.
Strong growth in third-quarter operating results
Alongside these disposals, Pandox published quarterly results showing substantial growth in revenue and operating earnings.
| Metric | Q3 2026 | Q3 2025 | Change |
|---|---|---|---|
| Total revenue | SEK 2,429 million | SEK 1,972 million | +23% |
| Net operating income | SEK 1,619 million | SEK 1,257 million | +29% |
| EBITDA | SEK 1,561 million | SEK 1,202 million | +30% |
| Cash earnings | SEK 806 million | SEK 617 million | +31% |
| Cash earnings per share | SEK 4.14 | SEK 3.17 | +31% |
This growth benefited in particular from the integration of assets acquired through the Dalata transaction and the strength of the Nordic hotel market, especially in Sweden.
On a like-for-like basis and at constant exchange rates, growth was more moderate: 4% for both revenue and net operating income.
This distinction is important when assessing the group’s underlying performance.
A significant proportion of reported growth stems from changes in the property portfolio rather than exclusively from improved performance at previously owned assets.
EBITDA rises 28% over the first nine months
The cumulative results for January to September confirm this momentum.
| Metric | 9M 2026 | 9M 2025 | Change |
|---|---|---|---|
| Revenue | SEK 6,299 million | SEK 5,393 million | +17% |
| Net operating income | SEK 4,112 million | SEK 3,246 million | +27% |
| EBITDA | SEK 3,950 million | SEK 3,087 million | +28% |
| Net profit | SEK 1,880 million | SEK 1,468 million | +28% |
| Cash earnings | SEK 1,817 million | SEK 1,503 million | +21% |
Growth in net operating income was primarily driven by the leased property segment.
Over the nine-month period, this segment generated SEK 3.488 billion, an increase of 35%.
By contrast, the Own Operations segment, comprising hotels operated directly by Pandox, recorded net operating income of SEK 624 million, down 5%.
This divergence highlights the different economic profiles of leased properties and hotels for which Pandox assumes direct operating responsibility.
Dalata and Revo Hospitality: Two major developments
The interim report also highlights two other significant matters for Pandox.
The first concerns Dalata, whose acquired assets are contributing significantly to growth in rental income.
Pandox states that the process of separating the property assets from the hotel operating business is progressing according to schedule.
The proposed sale of the operating platform to Scandic is expected to be completed in the fourth quarter of 2026.
The group then intends to refinance the credit facilities used to acquire Dalata through secured property financing, with credit margins expected to be significantly lower.
The second matter concerns Revo Hospitality Group, whose insolvency has prompted Pandox to reorganise nine German hotels previously leased to the operator.
Six hotels, comprising 1,243 rooms, have been transferred to direct operation by Pandox.
Three others, representing 616 rooms, remain operational under the insolvency proceedings, pending agreements with a new tenant.
These developments illustrate the risks inherent in the hotel owner-landlord model: while lease agreements can provide financial visibility, the failure of an operator may force the property owner to assume operational responsibilities temporarily.
A property portfolio approaching SEK 97 billion
As at 30 September 2026, Pandox owned 191 hotel properties comprising 42,393 rooms across eleven countries.
The market value of its portfolio stood at SEK 96.883 billion.
The United Kingdom was its largest market by value, followed by Germany, Sweden and Ireland.
The group also reported an average valuation yield of 6.32% for its leased property portfolio, while the average valuation yield for the entire portfolio was 6.39%.
These figures provide an interesting point of comparison with the implied yield of approximately 6.2% on the properties being sold, although the underlying scopes and calculation methodologies are not strictly identical.
The announced combined property value of the seven hotels represents approximately 2.2% of the portfolio’s value as at 30 September, before completion of the transactions.
LTH Analysis | Pandox rotates assets to regain financial flexibility
Pandox’s announcement comes at a time when the group is combining revenue growth and the integration of a major acquired portfolio with increasing pressure on financing costs.
The disposal of seven hotels is therefore not an isolated transaction.
It forms part of a capital allocation strategy combining acquisitions, asset repositioning, refinancing and deleveraging.
Three aspects are particularly noteworthy.
First, the ability to sell above book value. This demonstrates investor demand for certain Nordic hotel properties, without providing sufficient evidence to conclude that the market as a whole is experiencing a general increase in valuations.
Second, the implied transaction yield of approximately 6.2%. This provides a tangible benchmark for the valuation of the portfolio being sold and can be compared, with appropriate caution, against the property yields reported by Pandox.
Third, the expected reduction in LTV from 52.2% to 51.2%. In an environment of higher financing costs, this reduction helps preserve the group’s financial flexibility.
The transaction also illustrates a geographical shift: in Denmark, Pandox is now prioritising three properties in central Copenhagen.
The central question is therefore not simply how much Pandox will receive from selling seven hotels, but what combination of yield, tenant risk, property quality and financial capacity the group wishes to retain within its portfolio.
At a Glance
Company: Pandox AB, Stockholm.
Announcement date: 22 October 2026.
Transaction: Agreements to sell seven hotel properties in two transactions.
Geographies: Denmark and Sweden.
Total rooms: 1,248.
Underlying property value: Approximately SEK 2.1 billion, before deferred tax.
Buyers: Alma Property Partners and Midstar AB (Denmark); Västerkulla Hotell AB (Sweden).
Annual net operating income of properties being sold: Approximately SEK 130 million.
Implied yield: Approximately 6.2%, based on announced figures.
Expected closing: Q4 2026.
Pandox Q3 2026 EBITDA: SEK 1.561 billion, up 30%.
Net loan-to-value: 52.2% at 30 September 2026; 51.2% adjusted for the announced disposals.
Portfolio at 30 September: 191 hotel properties, 42,393 rooms, approximately SEK 96.9 billion in market value.
LTH perspective: Active asset rotation and debt reduction amid portfolio growth and higher financing costs.