
For a long time regarded as a niche, branded residences have established themselves in recent years as a fully fledged asset class within the hotel industry. The number of projects worldwide has risen from 169 in 2011 to more than 600 today, with an increasing share of that momentum driven by Southeast Asia and the Middle East. It is against this backdrop that the Future Hospitality Summit is evolving its dedicated format for the sector.
Demand driven as much by experience as by investment
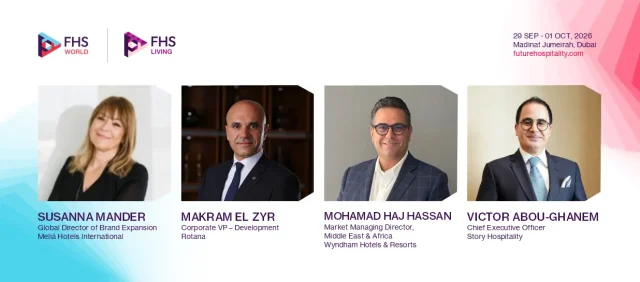
For Susanna Mander, Global Director of Brand Development at Meliá Hotels International, the segment’s growth is not purely financial — it is also emotional. Today’s buyers are not simply purchasing property, she explains; they are buying into a lifestyle, a sense of belonging and a trusted experience. She notes that the pandemic accelerated the search for flexibility, wellbeing and community, while owners and investors have come to recognise hotel brands’ ability to bring operational expertise, credibility and long-term asset management.
Makram El Zyr, Senior Vice President of Development at Rotana, traces this shift to evolving buyer expectations. Buyers, he says, are no longer looking simply for a place to live, but for quality, comfort and peace of mind — pointing to the importance of wellness amenities and shared spaces within a home designed to look after its occupants, in the manner of an upscale hotel.
Saudi Arabia and the UAE, regional engines of development
According to Mohamad Haj Hassan, Managing Director for the Middle East and Africa at Wyndham Hotels & Resorts, the appeal of Saudi Arabia and the UAE rests on a combination of ambitious national strategies, investor-friendly reforms and strong local and international demand. In Saudi Arabia, the transformation driven by Vision 2030 is giving rise to new destinations where hospitality and residential development are progressing hand in hand, exemplified by the giga-projects The Red Sea Project and AMAALA, which embed branded residences within their masterplans.
In the UAE, Dubai and Abu Dhabi have established themselves as global hubs for attracting wealth and international capital, a dynamic illustrated by projects such as Emirates Palace, Mandarin Oriental Mansions in Abu Dhabi. Mohamad Haj Hassan notes that branded residences there consistently command price premiums over non-branded units, reinforcing their dual appeal as both lifestyle and investment propositions.
Victor Abou Ghanem, Managing Director of STORY Hospitality, shares this analysis, highlighting the combination of ambitious national tourism visions and sustained local and international demand for quality real estate. For many buyers, he observes, Riyadh, Jeddah, Dubai and Abu Dhabi now sit within the same investment conversation as Miami, Singapore or London — pointing also to the region’s tax efficiency and its connectivity with Europe, Asia and Africa.
🔗 Read more on LTH: Branded Residences, quand l’hôtellerie réinvente la propriété
Lifestyle or returns: two rationales converging
Makram El Zyr describes a demand base with two distinct drivers. Some buyers are drawn by the lifestyle and status associated with branded residences, while others approach the purchase as a calculated investment, attracted by sale prices and rental income that are generally higher than for non-branded properties. The brand, he says, acts as a mark of quality that protects value over time.
Mohamad Haj Hassan nuances this balance by market: investor-driven demand remains particularly strong in the UAE, fuelled by the continuing inflow of international capital, while in Saudi Arabia lifestyle aspirations play a more prominent role, in step with the social and economic transformation driven by Vision 2030.
Choosing a brand: a strategic decision above all
For Victor Abou Ghanem, selecting a partner brand should not be a popularity contest but a strategic choice. An international brand brings trust, systems, distribution and loyalty programmes, but success also depends on its ability to understand local ways of living — privacy, family gatherings, or the use of outdoor spaces. STORY Hospitality applies three tests: does the brand genuinely know how to manage lived-in residences, beyond hotel operations alone? Does it resonate with the targeted buyers? And can it adapt its design and service to the local culture while remaining true to its identity?
At Meliá, Susanna Mander stresses the balance between global recognition — a guarantee of trust and distribution — and authenticity, a source of emotional connection and lasting differentiation. The brand must adapt to the destination, not the other way round, she says, pointing to the integration of local culture, gastronomy and architectural design alongside the maintenance of international service standards.
Disciplined growth and differentiation
For Wyndham Hotels & Resorts, genuine differentiation today rests on the strength of the brand ecosystem rather than simply attaching a name to a project. Mohamad Haj Hassan highlights the group’s global network of more than 8,300 hotels and the Wyndham Rewards loyalty programme, which support demand generation and international visibility for residential projects. However, he stresses that growth must remain disciplined, with every project required to deliver real value to both owners and residents without compromising brand integrity.
Susanna Mander shares this approach: it is not logos that create value, she says, but operational excellence and emotional engagement. She points to Meliá’s more than seventy years of experience in understanding guest service and behaviour, and maintains that growth must stay disciplined and targeted, focused on destinations where the group can genuinely add value rather than expanding for scale alone.
Mixed-use ecosystems: the key to placemaking
At Rotana, mixed-use environments — retail, dining, wellness, culture — are now seen by residents as a baseline expectation rather than an added extra. Makram El Zyr explains that the right balance depends on location, available space and design, and that the most successful projects are those that function as genuine destinations rather than towers with a handful of additional amenities.
Victor Abou Ghanem observes that branded residences rarely reach their full potential as standalone towers in the Middle East. Integrated into mixed-use ecosystems combining hospitality, retail, dining, culture, wellness and public spaces, they play an active role in placemaking: unlike transient hotel guests, resident owners animate neighbourhood life beyond seasonal tourism peaks and sustain steady demand for local shops and services.
Dubai awaits for FHS Living, 1 October
The Branded Residences Forum, a flagship event of the Future Hospitality Summit, returns under a new identity, FHS Living, as part of FHS World, running from 29 September to 1 October 2026 at Madinat Jumeirah, Dubai. The day on 1 October will cover the full spectrum of residential asset classes — branded residences, student housing, senior living, co-living, fractional ownership, club concepts and mixed-use projects — with participation from leading figures across the sector.
Asked about the future of the segment, all four executives converge on a shared view: authentic lifestyle communities where hospitality, culture, wellbeing and real estate come together to create lasting value; a standard that is now shaping quality residential development more broadly; and a fusion of global hotel brands with locally rooted lifestyle communities, set to become a mainstream component of the international residential market.
At a glance by The Hospitality Tribune
Branded residences move from niche to mainstream asset class across the Middle East.
FHS Living, the rebranded Branded Residences Forum, takes place 1 October 2026 in Dubai, part of FHS World (29 September – 1 October, Madinat Jumeirah)
Global branded residences pipeline grew from 169 projects in 2011 to over 600 today, driven by lifestyle demand and hospitality brand credibility
Saudi Arabia: Vision 2030 giga-projects, including The Red Sea Project and AMAALA, embed branded residences into large-scale masterplans
UAE: Dubai and Abu Dhabi remain global wealth-migration hubs; branded units consistently command pricing premiums over non-branded stock
Wyndham’s global network exceeds 8,300 hotels, reinforcing distribution and demand generation for its residential offering
Executives from Meliá, Rotana, Wyndham and STORY Hospitality stress disciplined growth over scale, prioritising brand integrity and long-term partnerships