
Key third-quarter performance indicators
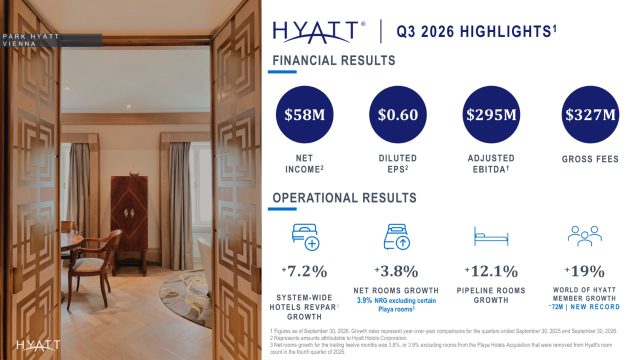
Net income attributable to Hyatt reached US$58 million, while adjusted net income stood at US$122 million. Diluted earnings per share were US$0.60, compared with adjusted diluted earnings per share of US$1.27.
The asset-light model supports fee growth
Fee growth is one of the main takeaways from the quarter.
Base management fees increased by 10%, incentive management fees rose by 21.9%, and franchise fees and other related revenues grew by 16.8%.
This performance reflects, in particular, the results of US properties, new hotel openings and management agreements arising from the acquisition of Playa Hotels & Resorts.
Mark S. Hoplamazian, Chairman, President & CEO of Hyatt, highlights the strength of the group’s brands and its management- and franchise-based business model.
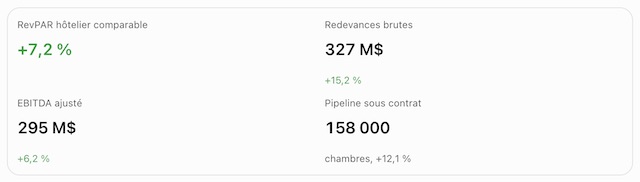
Adjusted EBITDA increased by 6.2% on a reported basis, but by 19% after adjusting for the effects of assets disposed of in 2025.
This distinction is important when assessing changes in the group’s operating perimeter.
Luxury and the United States perform strongly, while all-inclusive results are more mixed
The luxury segment was the main driver of hotel RevPAR growth in the third quarter.
In the United States, RevPAR increased by 8.2%, benefiting in particular from the FIFA World Cup and calendar-related effects.
By contrast, Net Package RevPAR at all-inclusive resorts declined by 2.5%, primarily due to softer demand in certain Mexican destinations.
This decline was partially offset by performance in the Caribbean and Europe.
Nevertheless, Hyatt expects this indicator to return to growth in the fourth quarter.
Development: a record pipeline of 158,000 rooms
Hyatt reports a pipeline of approximately 158,000 rooms covered by executed management or franchise agreements, representing a year-on-year increase of 12.1%.
During the quarter, the group opened 3,808 rooms.
Openings included Hyatt Vivid Punta Cana, the brand’s first property in the Dominican Republic; Beldersoy Resort and SPA in Uzbekistan, under the Destination by Hyatt brand; and Thompson Seville in Spain.
Net room growth over the preceding twelve months reached 3.8%, or 3.9% excluding the impact of rooms acquired through Playa Hotels that were removed from the portfolio at the end of 2025.
2026 outlook: Hyatt raises its guidance
| Indicator | 2026 forecast |
|---|---|
| Comparable hotel RevPAR growth | +5% to +5.5% |
| Net room growth | Approximately +6% |
| Gross fees | US$1.320–1.335 billion |
| Adjusted EBITDA | US$1.170–1.200 billion |
| Net income attributable to Hyatt | US$240–310 million |
| Adjusted free cash flow | US$580–630 million |
| Shareholder returns | US$375–425 million |
The group expects full-year adjusted EBITDA to increase by 14% to 17% against a 2025 base adjusted for changes in the portfolio perimeter.
Hyatt has also raised its shareholder return target, having spent US$147 million on share repurchases during the third quarter.
As of 30 September, total debt stood at US$4.4 billion, with available liquidity of approximately US$1.8 billion.
LTH Analysis | The transformation of Hyatt’s business model becomes visible in its results
The third quarter of 2026 highlights the evolution of Hyatt’s financial and operating profile.
Fee growth, which exceeded the increase in reported adjusted EBITDA, illustrates the growing importance of management and franchise revenues within the group’s business model.
The disposal of the property portfolio acquired from Playa Hotels, completed at the end of 2025, forms part of this transformation, prioritising long-term contractual revenues over direct asset ownership.
However, the decline in Net Package RevPAR in certain destinations is a reminder that the asset-light model does not eliminate exposure to demand cycles.
For investors, three indicators will warrant particular attention: the conversion of the development pipeline into actual hotel openings, continued fee growth and the group’s ability to translate that growth into free cash flow.
With a record pipeline and strengthened full-year guidance, Hyatt has significant opportunities for further development. Their contribution to profitability and cash generation will remain decisive.
Source: Hyatt Hotels Corporation, third-quarter 2026 results, 29 October 2026.
At a Glance
RevPAR: Comparable system-wide hotel RevPAR increased 7.2% in Q3 2026.
Gross fees: Up 15.2% to US$327 million.
Profitability: Adjusted EBITDA reached US$295 million, up 6.2%.
Development: The executed pipeline reached approximately 158,000 rooms, up 12.1%.
All-inclusive: Net Package RevPAR declined 2.5%, primarily reflecting softer demand in Mexico.
Outlook: Hyatt forecasts full-year adjusted EBITDA of US$1.17–1.20 billion.